How to use NVDA Direction parameters with VWAP
Contact customer support at support@nvdadirection.com
UNDERSTANDING VWAP WITH NVDA DIRECTION
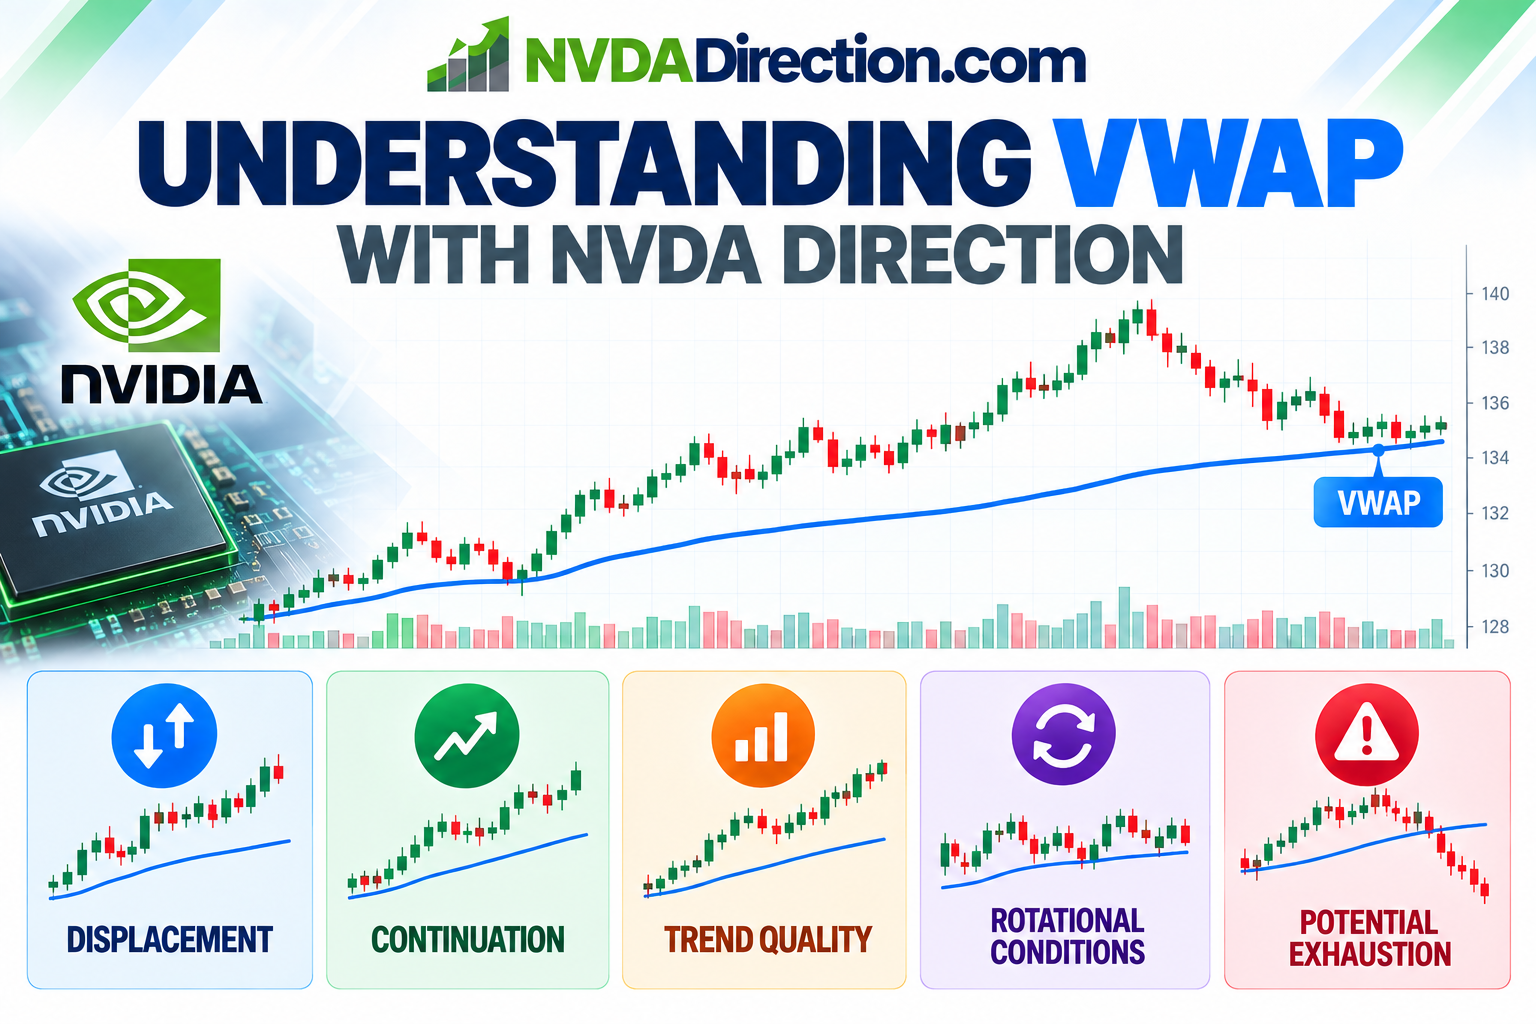
This training material is designed to help members better understand the underlying concept behind VDI (VWAP Displacement Index).
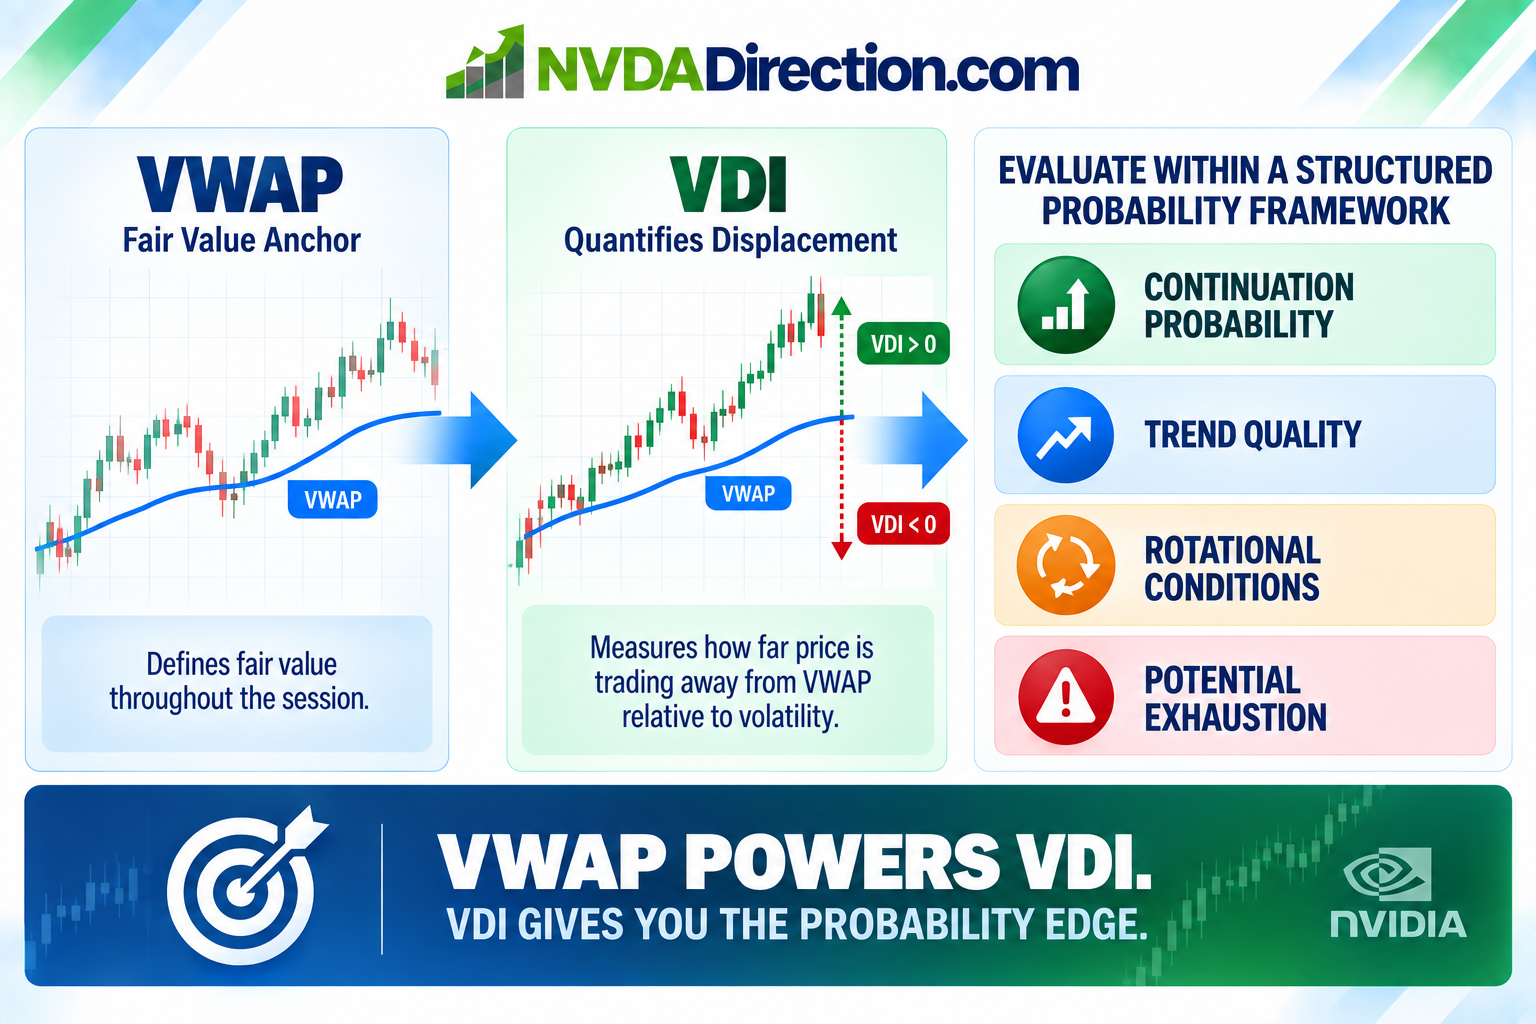
VWAP itself is NOT a standalone NVDA Direction framework.
Instead, VWAP acts as the fair value anchor used inside the VDI calculation.
Understanding how VWAP behaves helps members better interpret:
-
displacement
-
continuation
-
trend quality
-
rotational conditions
-
potential exhaustion
🧠 WHAT VWAP ACTUALLY REPRESENTS
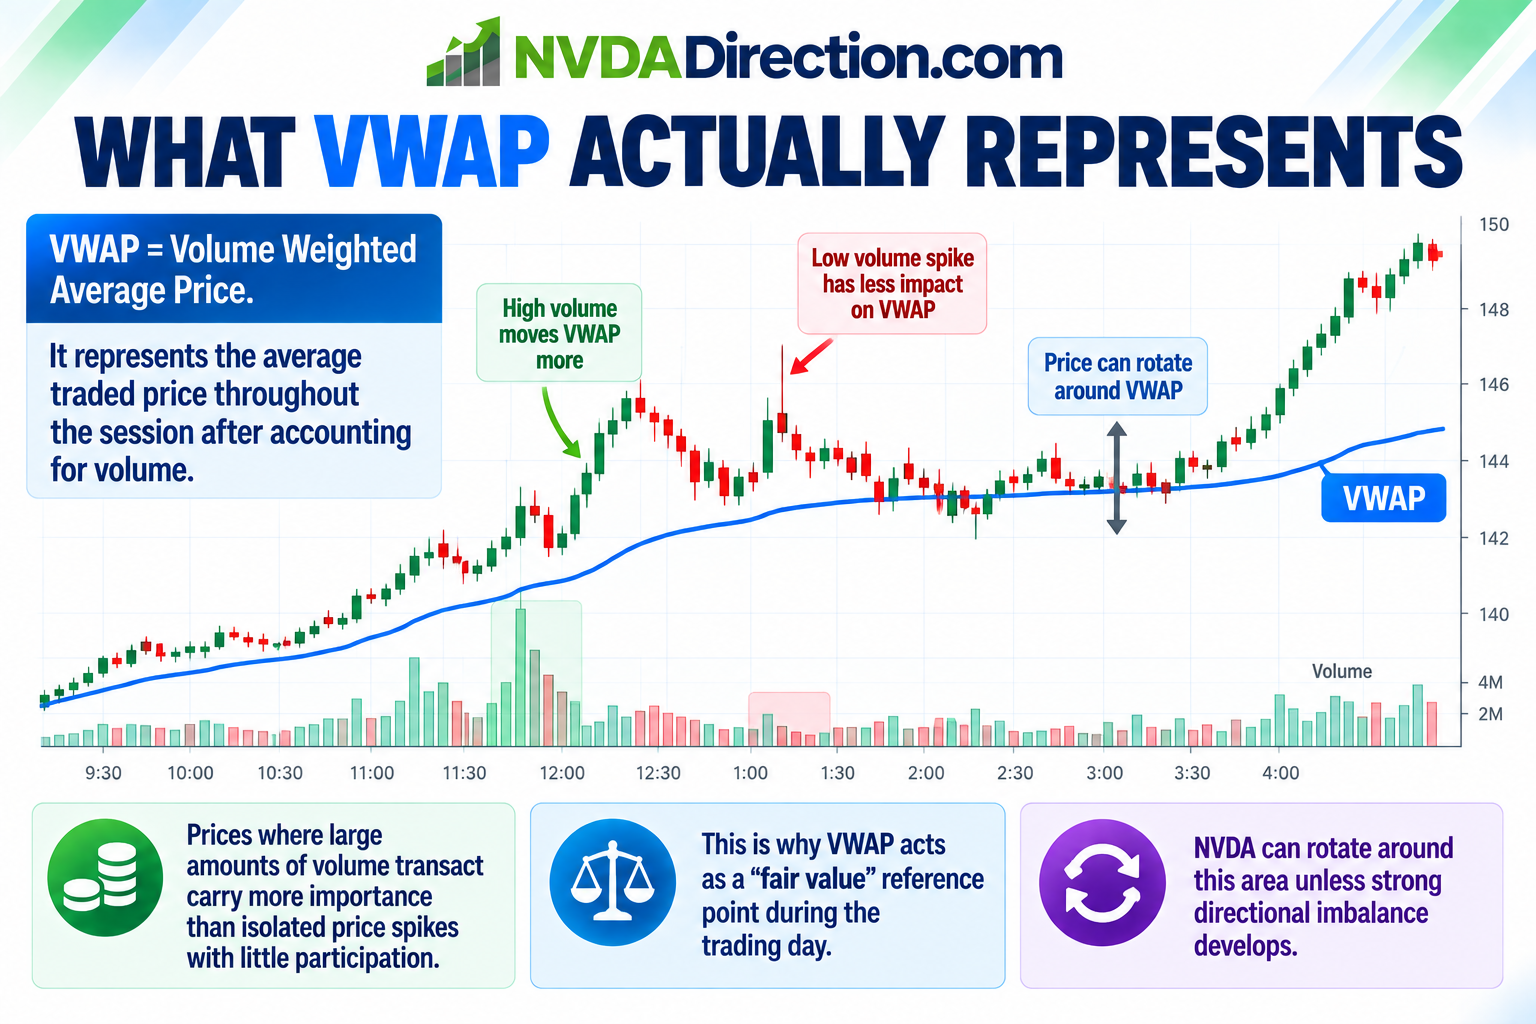
VWAP = Volume Weighted Average Price.
It represents the average traded price throughout the session after accounting for volume.
Prices where large amounts of volume transact carry more importance than isolated price spikes with little participation.
This is why VWAP acts as a “fair value” reference point during the trading day.
NVDA can rotate around this area unless strong directional imbalance develops.
🧠 WHY VWAP MATTERS FOR NVDA DIRECTION
The NVDA Direction framework already incorporates VWAP directly through:
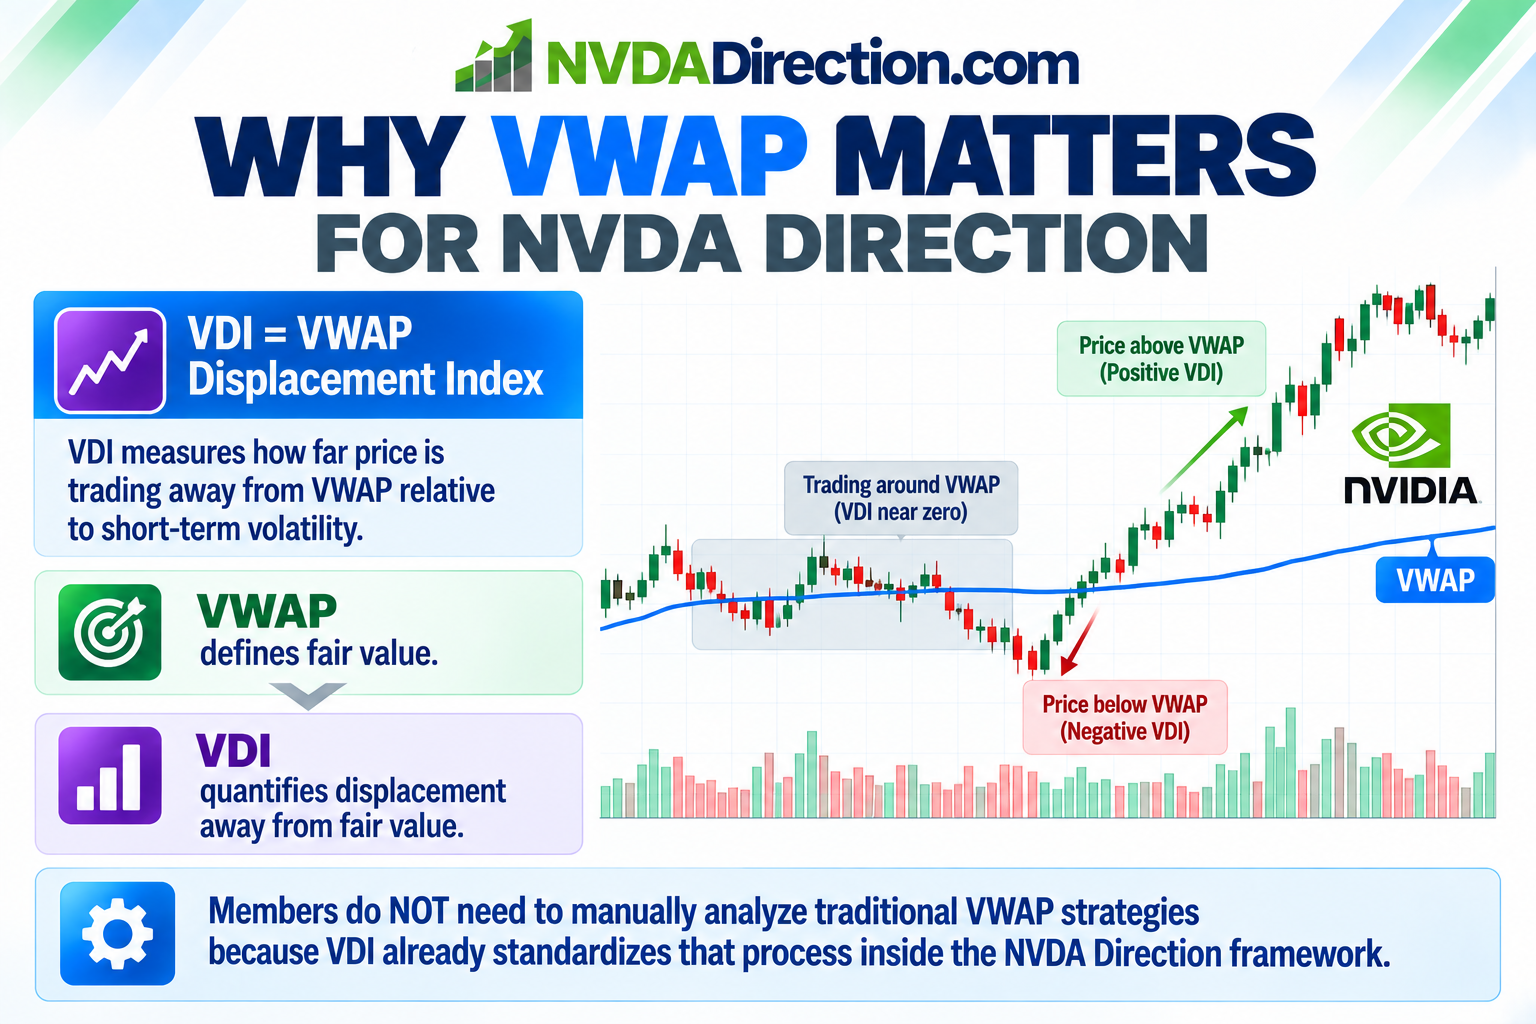
VDI = VWAP Displacement Index
VDI measures how far price is trading away from VWAP relative to short-term volatility.
This means:
-
VWAP defines fair value
-
VDI quantifies displacement away from fair value
Members do NOT need to manually analyze traditional VWAP strategies because VDI already standardizes that process inside the NVDA Direction framework.
🧠 UNDERSTANDING VWAP DISPLACEMENT
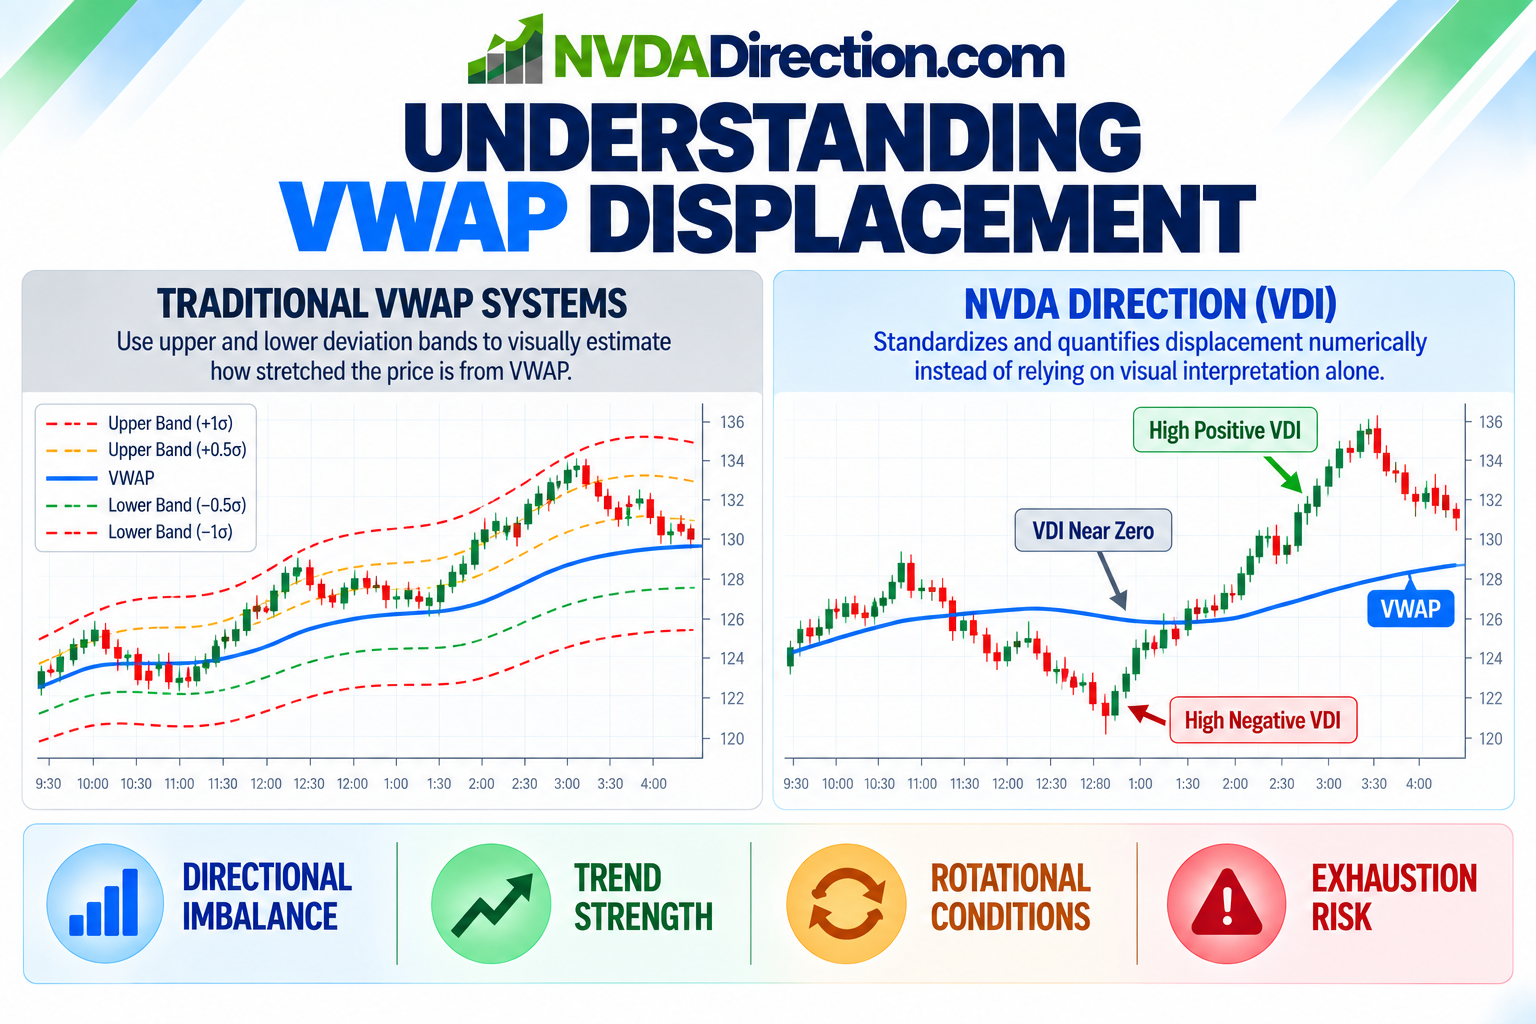
Traditional VWAP systems often use upper and lower deviation bands to visually estimate how stretched the price is from VWAP.
NVDA Direction approaches this differently.
Instead of relying on visual interpretation alone, VDI standardizes and quantifies displacement numerically.
This allows members to objectively measure:
-
directional imbalance
-
trend strength
-
rotational conditions
-
exhaustion risk
🧠 HOW VWAP BANDS RELATE TO VDI
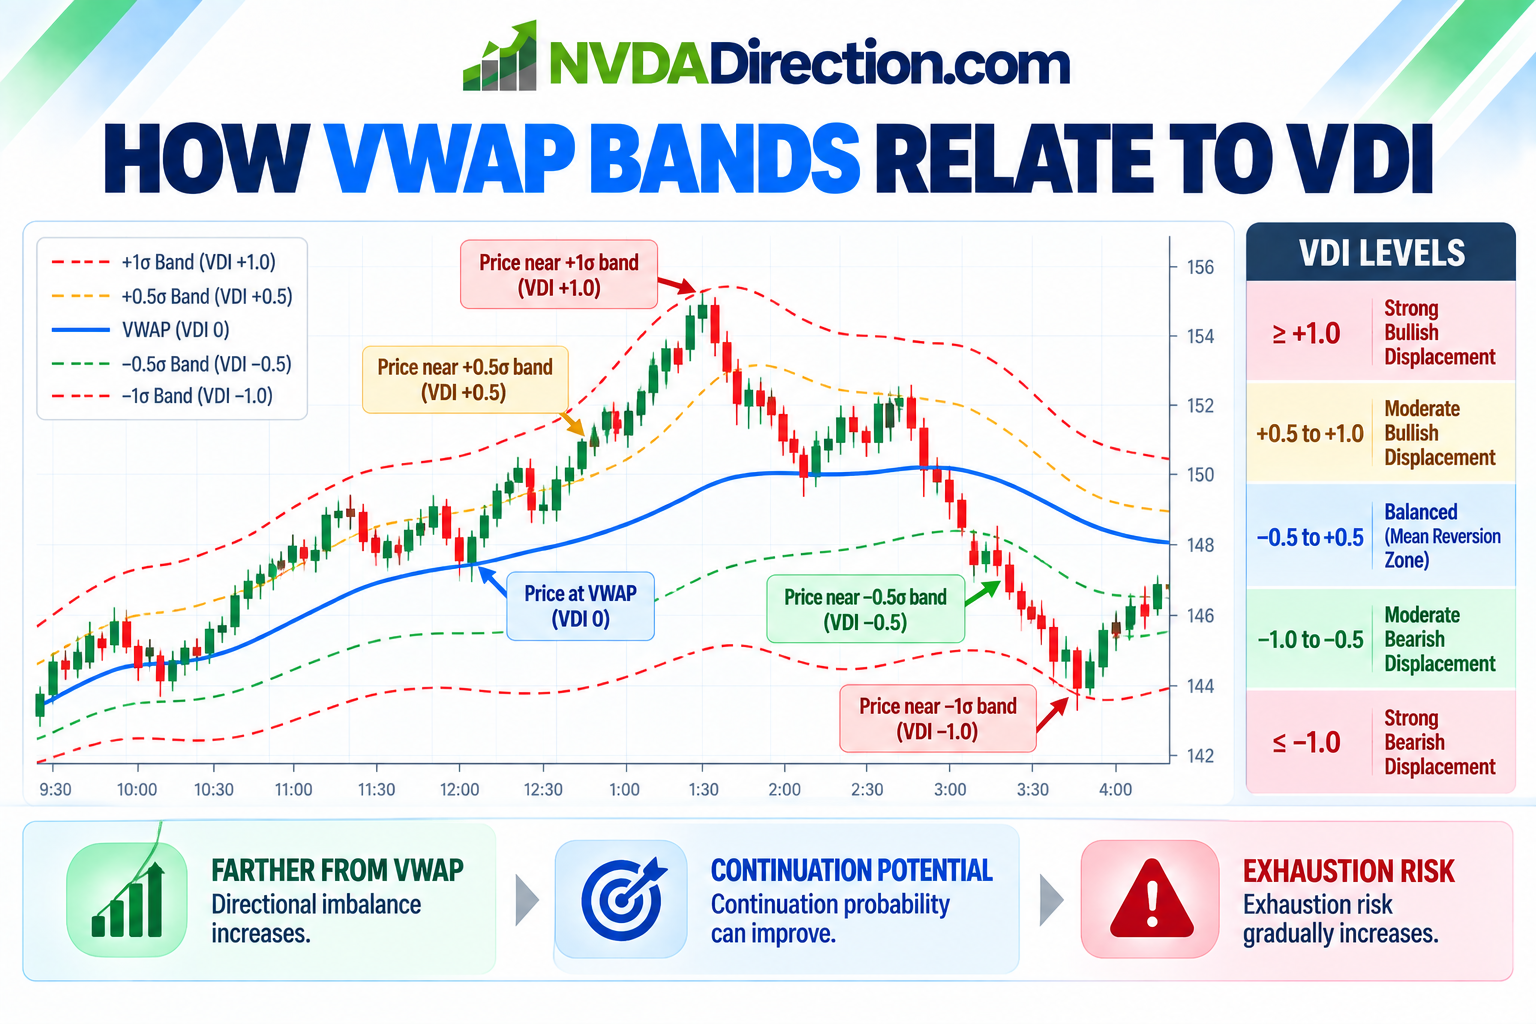
VWAP bands can still help members visually understand displacement around fair value.
As price moves farther away from VWAP:
-
directional imbalance increases
-
continuation probability can improve
-
exhaustion risk gradually increases
This behavior is exactly what VDI is measuring mathematically.
📊 LOW VDI CONDITIONS
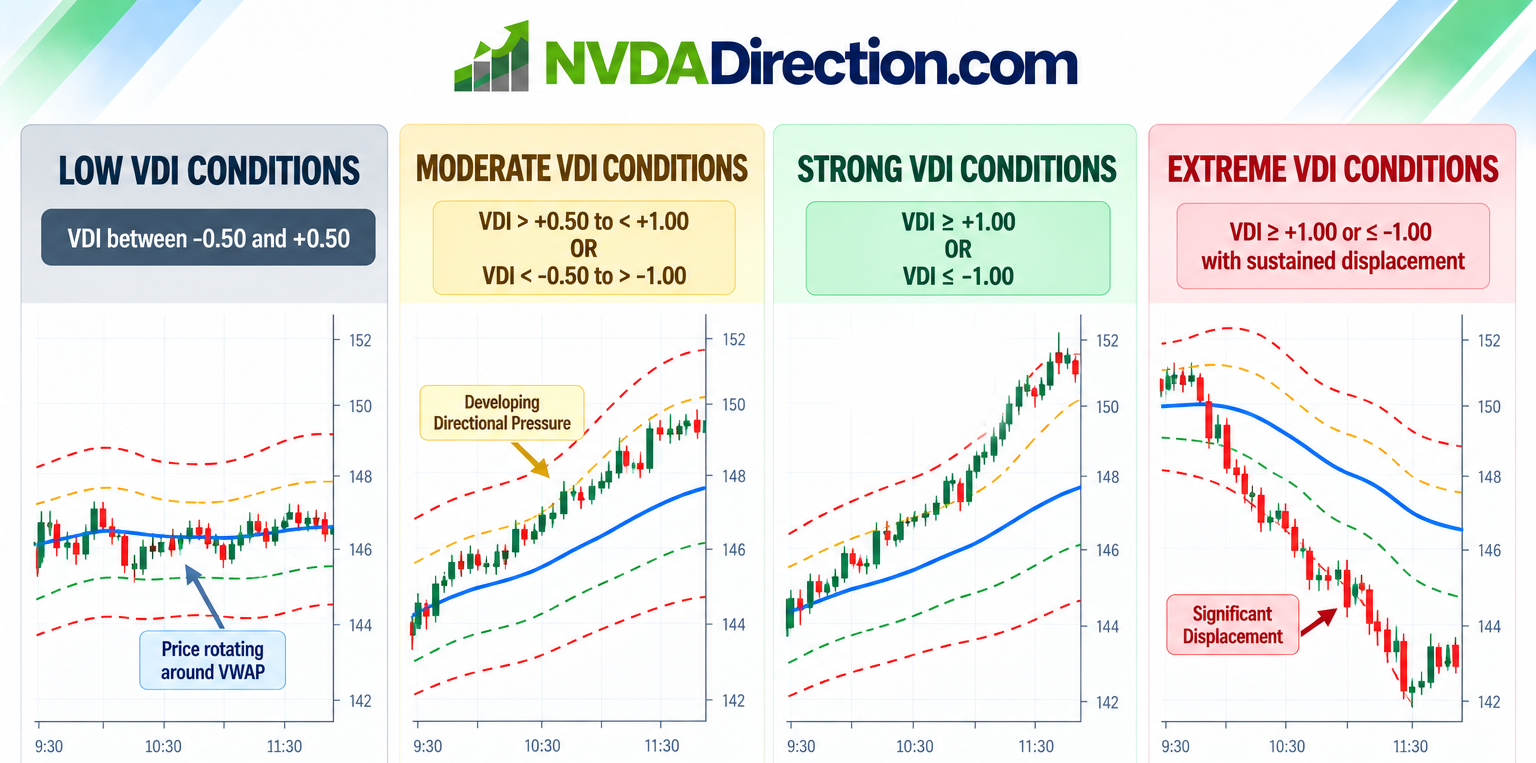
VDI between -0.50 and +0.50
This usually means:
-
price remains relatively close to VWAP
-
NVDA is in a balanced environment
-
rotational behavior can dominate
-
chop probability increases
Under these conditions:
-
fake breakouts become more common
-
mean reversion becomes more likely
-
continuation lacks conviction
Visually, this often resembles price rotating tightly around VWAP with limited expansion away from fair value.
📈 MODERATE VDI CONDITIONS
VDI > +0.50 to < +1.00
OR
VDI < -0.50 to > -1.00
This suggests:
-
directional pressure may be developing
-
imbalance is beginning to build
-
continuation still requires confirmation
This environment often represents transition conditions between balance and a stronger directional move.
🔥 STRONG VDI CONDITIONS
VDI ≥ +1.00
OR
VDI ≤ -1.00
This suggests:
-
price is meaningfully displaced from VWAP
-
directional imbalance is established
-
continuation probability can improve
Visually, this often resembles price holding cleanly away from VWAP with sustained directional displacement.
This is where higher-quality directional movement typically develops.
🚀 EXTREME VDI CONDITIONS
VDI ≥ +1.00 or ≤ -1.00 with sustained displacement
This suggests:
-
aggressive directional displacement exists
-
trend conditions are stronger
-
exhaustion risk can gradually increase
At these levels:
-
continuation may still occur
-
but reversal probability can increase if RVF or MA begin weakening
-
TPS should be monitored for confirmation
Visually, this often resembles price becoming significantly displaced from VWAP.
🧠 VWAP SLOPE AND MARKET STRUCTURE
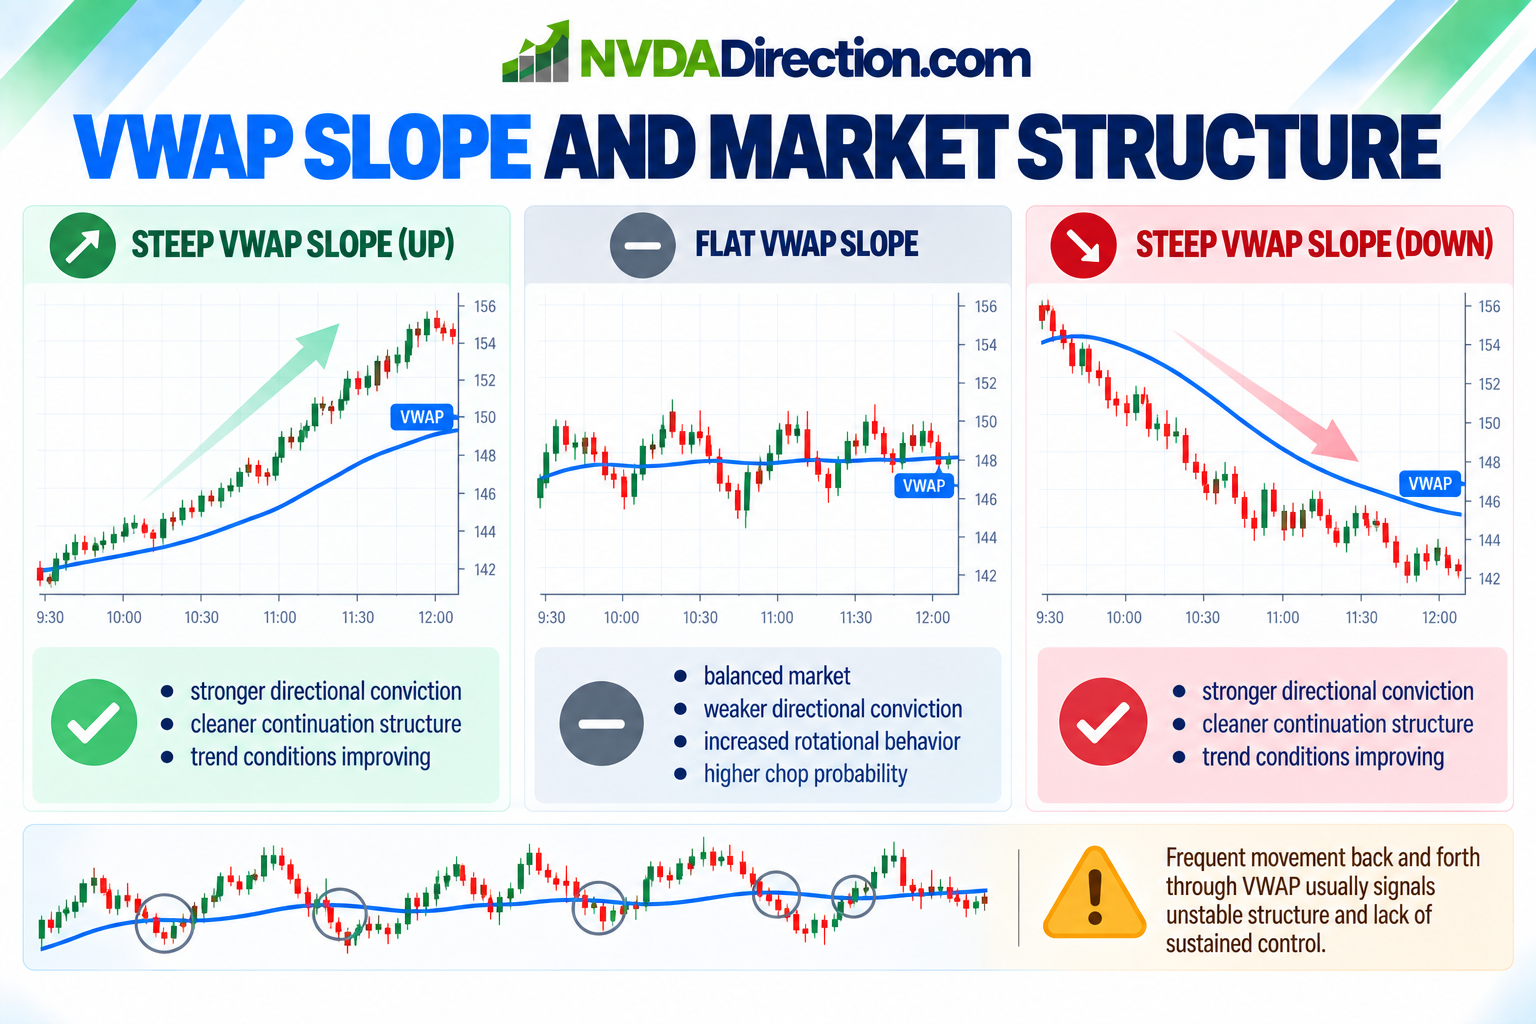
The slope of VWAP can help members better understand overall market structure.
✅ Steep VWAP slope
-
stronger directional conviction
-
cleaner continuation structure
-
trend conditions improving
✅ Flat VWAP slope
-
balanced market
-
weaker directional conviction
-
increased rotational behavior
-
higher chop probability
Frequent movement back and forth through VWAP usually signals unstable structure and lack of sustained control.
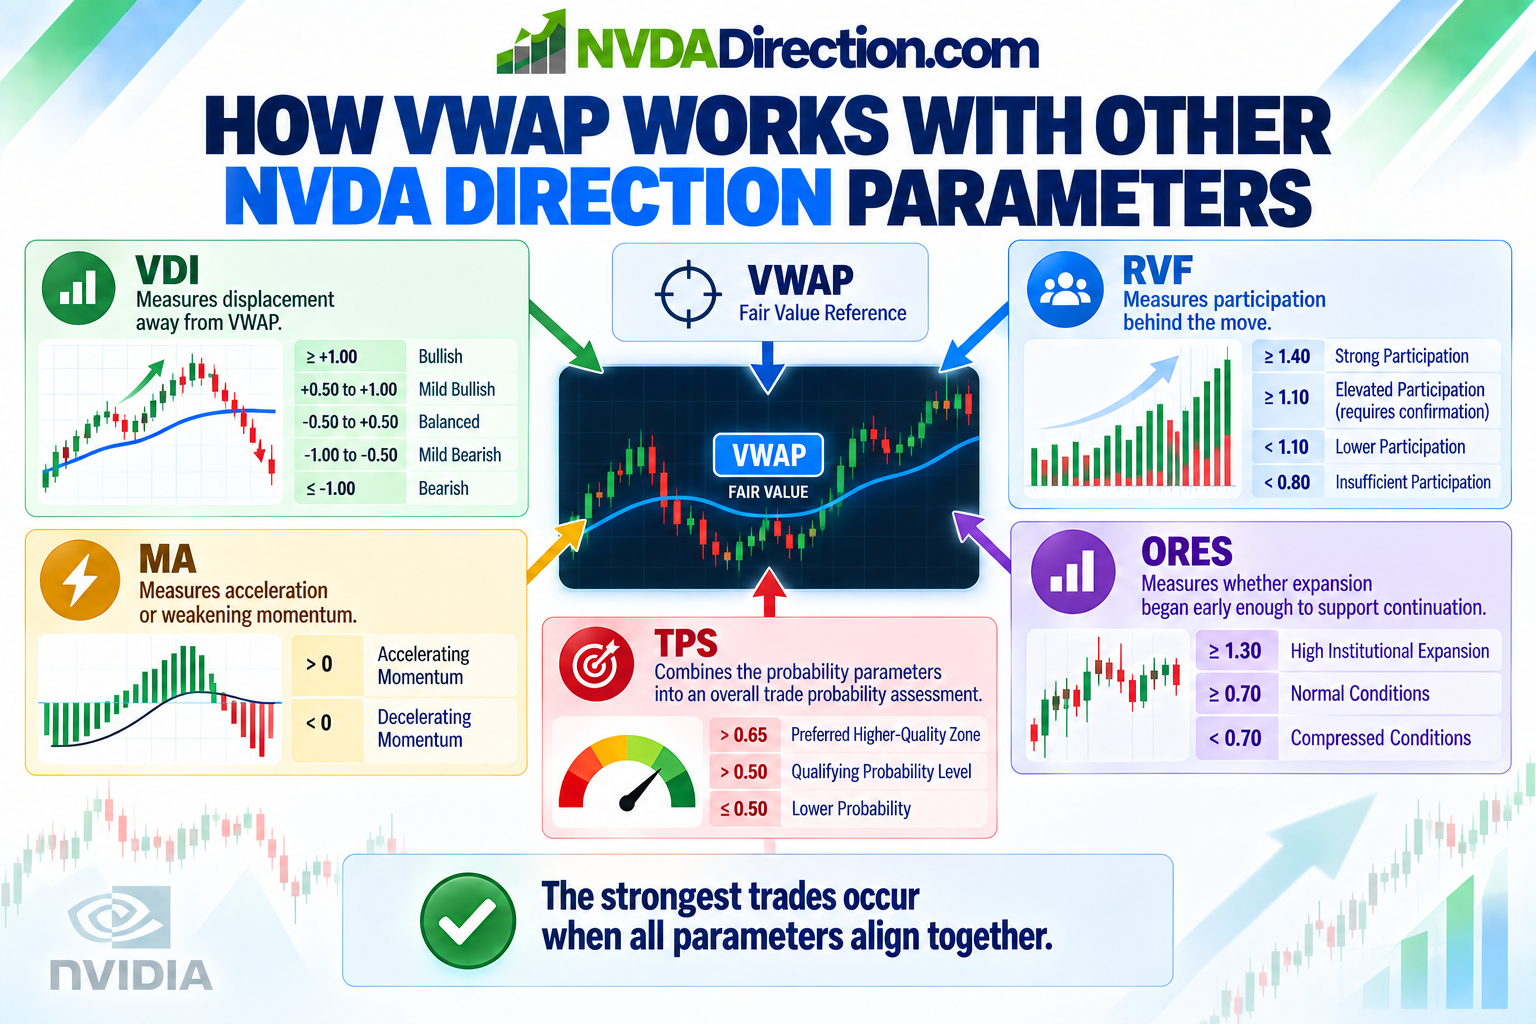
🧠 HOW VWAP WORKS WITH OTHER NVDA DIRECTION PARAMETERS
VWAP alone should never be used in isolation.
The NVDA Direction framework combines:
VDI
Measures displacement away from VWAP.
RVF
Measures participation behind the move.
RVF ≥ 1.40 represents strong participation, while RVF ≥ 1.10 represents elevated participation requiring confirmation.
MA
Measures acceleration or weakening momentum.
MA > 0 indicates accelerating momentum, while MA < 0 indicates decelerating momentum.
ORES
Measures whether expansion began early enough to support continuation.
ORES ≥ 1.30 indicates high institutional expansion, ORES ≥ 0.70 represents normal conditions, and ORES < 0.70 represents compressed conditions.
TPS
Combines the probability parameters into an overall trade probability assessment.
TPS > 0.50 provides a qualifying probability level, while TPS > 0.65 represents the preferred higher-quality zone.
The strongest trades occur when all parameters align together.
🧠 FINAL TAKEAWAY
VWAP is not a standalone NVDA Direction strategy.
Instead, VWAP serves as the underlying fair value anchor powering VDI.
NVDA Direction members use VDI to standardize and quantify displacement so they can evaluate:
-
continuation probability
-
trend quality
-
rotational conditions
-
potential exhaustion
inside a structured probability framework.
⏱️ NVDA DIRECTION TRADING WINDOW
Trading begins at 10:00 AM EST.
Best trading window: 10:00–11:30 AM EST.
Trading ends at 11:30 AM EST.
Within this window, VWAP and VDI should be evaluated together with RVF, MA, ORES, TPS and price structure rather than treated as standalone signals.